
Life Insurance for Health-Conscious Texans
You’re already putting in the work.
Your life insurance rate might notice.
$500,000 in life insurance?
It might cost less than your protein shake habit.
Healthy applicants can qualify for better rates.
- Licensed Texas Insurance Agent
- Independent, Multiple Carriers
- North Texas and DFW
- TX License # 1853547
How Underwriting Works
Your health can make a difference.
Life insurance companies look at more than your age. Your overall health, tobacco use, blood pressure, cholesterol, build, medical history and other factors can influence the rate you’re offered.
Staying active doesn’t automatically guarantee a preferred rate. But good overall health can put you in a better position when an insurer evaluates your application.
Blood Pressure
Healthy readings can be one factor insurers consider.
Cholesterol & Labs
Your overall health profile can influence underwriting.
Tobacco / Nicotine Use
Tobacco and nicotine use can have a significant effect on life insurance pricing.
Height & Weight
Carriers commonly evaluate build as part of the broader health picture.
Choosing an Amount
$500,000 sounds like a lot. Until you give it a job.
The right amount of life insurance depends on what you need the coverage to actually accomplish. Here is the kind of work a policy is usually asked to do.
Housing
Paying off or keeping up with a mortgage so your family can stay where they are.
Income Replacement
Replacing years of earnings, not just a single year, for the people who depend on them.
Childcare & Education
Day-to-day care while children are young, and school costs later on.
Debt & Final Expenses
Clearing loans and covering final costs instead of passing them along.
Household Running Costs
Groceries, utilities, insurance and everything else that does not pause.
Time to Adjust
Room for a surviving spouse or family to make decisions without financial pressure.
Existing Coverage
What you already have through work or an older policy counts toward the total.
Your Own Priorities
Whatever matters most to you that the list above does not capture.
The right amount isn’t the same for everyone. $500,000 is simply a useful starting point for the conversation, not a recommendation for your situation.
A Common Question
“I already have life insurance through work.”
That’s a good place to start. It may not be where you want to stop.
It may be less coverage than you think.
Many workplace plans provide a fixed benefit or a multiple of salary. That amount may not be enough to replace years of income, cover housing, or support the people who depend on you.
Your job can change.
Employer-sponsored coverage is tied to the employer’s benefits package. If employment changes, the coverage or cost may change as well. Some plans may allow conversion or continuation, but terms vary.
Your own policy gives you another layer of protection.
Individually owned life insurance is not dependent on remaining with a particular employer. Personal coverage can complement workplace benefits and give the insured more control over the amount and duration of protection.
Keep the coverage through work.
Just make sure it’s enough.
Not sure what you have? I can help you look at your workplace coverage and see whether there’s a gap.
Timing
Your health matters. So does timing.
Life insurance generally becomes more expensive as you get older. Changes in health can also affect what you qualify for later.
That doesn’t mean you’ve missed your chance if you’re in your 40s, 50s or beyond. It simply means there can be value in looking at your options while your health is working in your favor.
Protect what you’ve built.
Not sure how much coverage you need?
Your Advisor
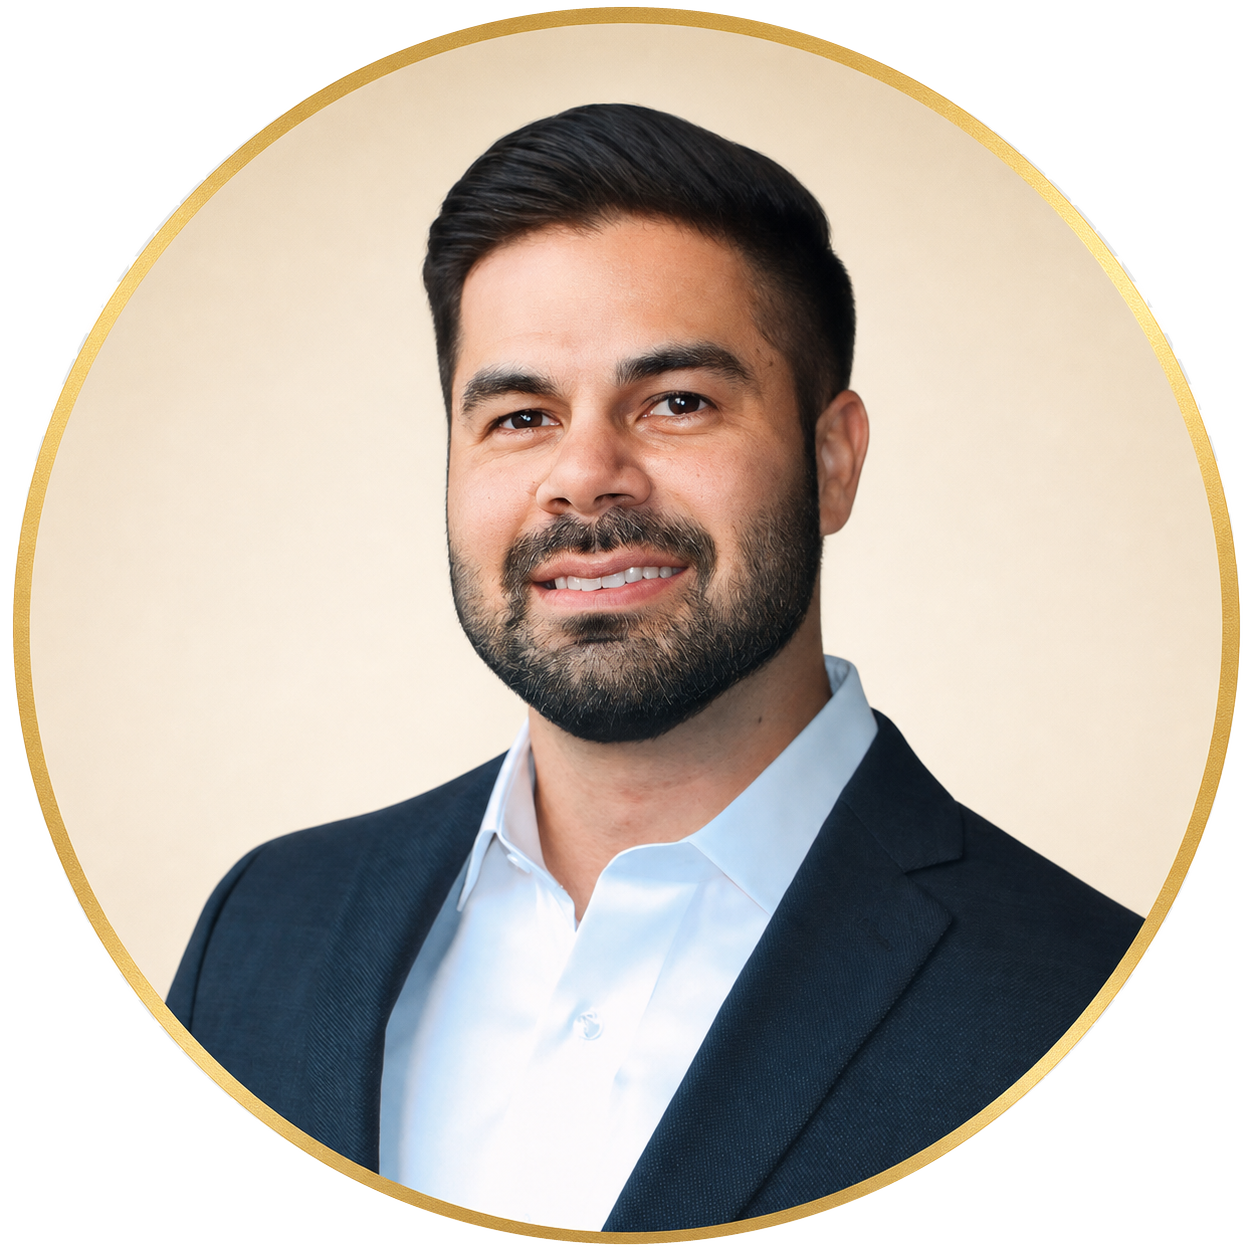
Hi, I’m Luke.
Luke Faulkner · Licensed Texas Insurance Agent · Gilded Oak Insurance · TX License #1853547
I’ll help you look at the numbers, understand what different coverage amounts could actually do for your family, and compare your options without turning it into a sales pitch.
For broader educational guidance, see Gilded Oak’s Texas Life Insurance guide.
See what you may qualify for
A few quick details. This is not an application, and there is nothing to sign.
Takes about 5 minutes.
Prefer to reach out directly?
Submitting this form does not obligate you to buy anything, and it is not an application for insurance. Your information is used to review and discuss coverage options in accordance with our Privacy Policy. See our Privacy Policy and Terms & Conditions.
Questions
Frequently asked questions
No. Exercise alone does not determine your rate. Insurers look at your broader health profile and other underwriting factors. Good overall health can help some applicants qualify for more favorable rates.
It depends on the carrier, applicant, coverage amount, and underwriting path. Some applicants may qualify through accelerated or no-exam underwriting.
That depends on income, debts, housing, family responsibilities, existing coverage, and what you want the policy to accomplish.
Yes. Employer-sponsored coverage and individually owned life insurance can work together. The useful question is how much coverage you already have, how much you need, and whether there is a gap.
Age is one factor in pricing, but it does not mean someone should assume coverage is unaffordable. Comparing available options is the better way to find out.
Protect what you’ve built.
See what coverage could look like for you.
Auto • Home • Life • Business